

Bank of England Bank Rate
3.75%  4.00%
Up 0.25 percentage points on 5 November 2026
If you let property in Manchester, are coming to the end of a fixed mortgage deal or are looking to buy, start by checking how your borrowing is priced. Here’s how the rise fits into the past 25 years and what to check on your mortgage.
How do UK and euro area rates compare over 25 years?
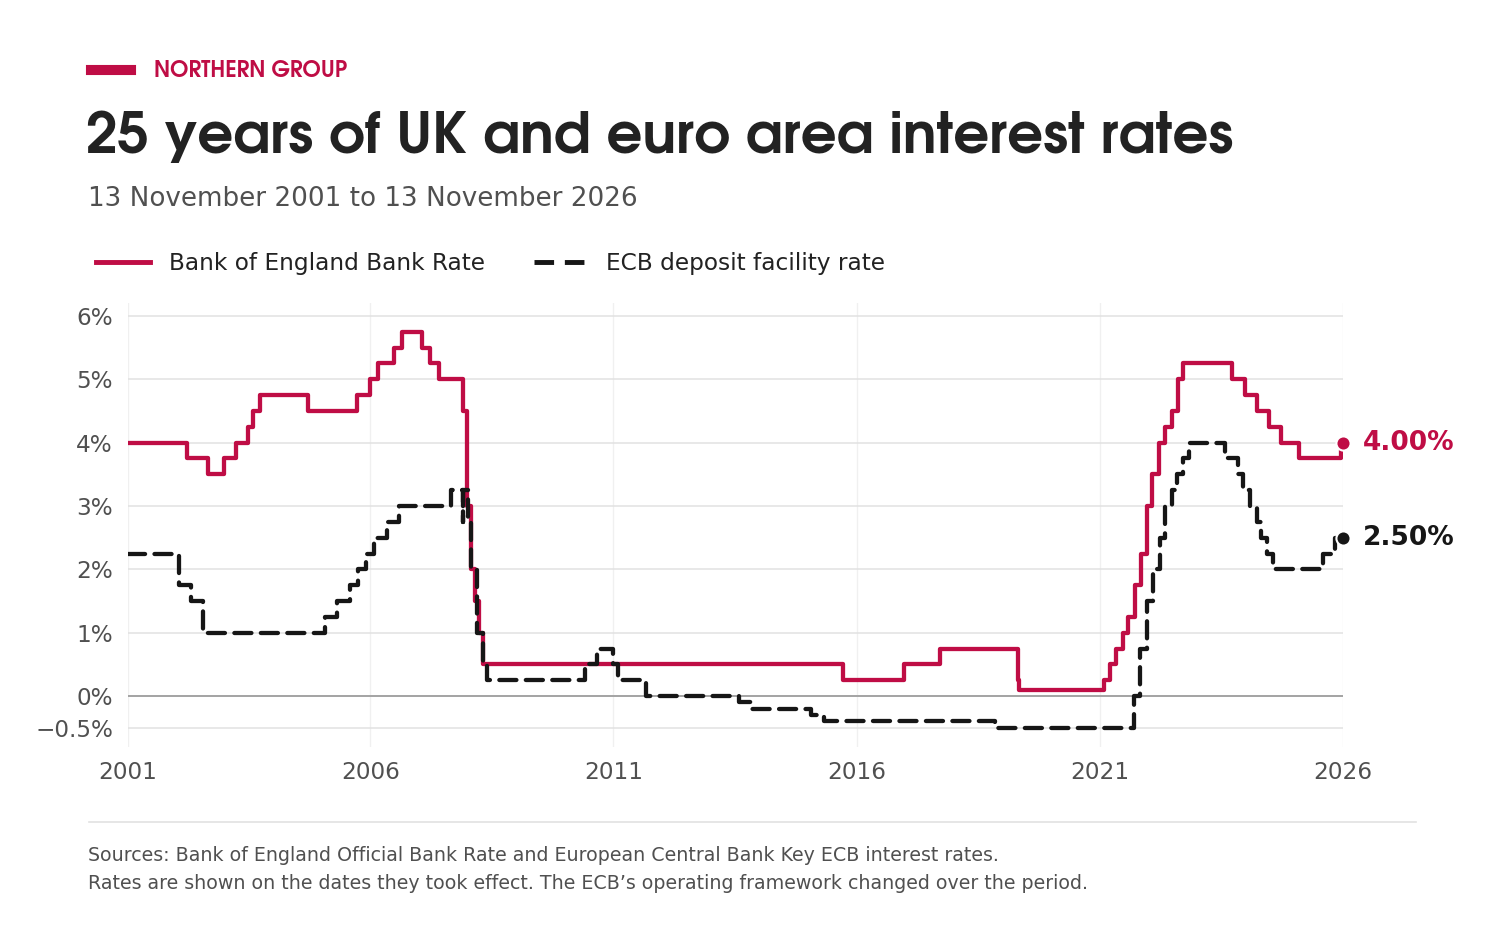
Why has the Bank of England raised interest rates?
Higher global energy prices were a major factor. UK inflation reached 3.5% in September, above the Bank’s 2% target. Eight of the nine Monetary Policy Committee members backed a quarter-point rise, while one preferred a half-point rise. The next decision is due on 17 December. Read the Bank of England’s full November decision.
Will your mortgage payments change?
| Mortgage type | What changes |
|---|---|
| Fixed rate | Your rate holds until the fixed term ends. Check the rate you’ll move onto and compare new deals, including fees. |
| Bank Rate tracker | The rise normally feeds through according to your terms. Check the lender’s notice for the new payment and start date. |
| Standard variable rate | Your lender decides whether, when and by how much to change your rate. |
About £42 more a month
The extra interest on a £200,000 interest-only loan if the full quarter-point rise passes through, before fees.
How it’s calculated
£200,000 × 0.0025 ÷ 12 = £41.67 in extra monthly interest.
New fixed-rate offers also reflect market expectations and lender pricing, so they can move by a different amount. MoneyHelper explains how rate changes affect different mortgages.

Start with your mortgage end date, your current rent and what the property actually costs to run.
What should Manchester landlords and buyers check now?
- Find your mortgage end date. Check what happens when the deal ends and budget for the payment you’d make at a higher rate.
- Review rent and running costs. For an apartment in Ancoats or New Islington, include the service charge alongside insurance, maintenance and time between tenancies. Use our guide to improving rental returns to check the costs that can affect cash flow.
- Check the numbers before buying. If you plan to let the property, compare rents for similar homes nearby. Include product fees when comparing mortgages. A broker can help you compare the borrowing options available to you.
Letting a property in Manchester?
We can give you a view on what your property could rent for and help with marketing, lettings and day-to-day management.
Speak to our Landlord Services team
Looking to buy? Browse Manchester properties for sale.